You took out a home equity line for a reason. A remodel. A medical bill. A rough year.
Now you’re thinking about selling, and you’re wondering whether that second loan just made everything complicated.
Usually, it didn’t. Selling a house with a HELOC or second mortgage is very common. It mostly comes down to math.
How a Second Loan Gets Paid Off When You Sell
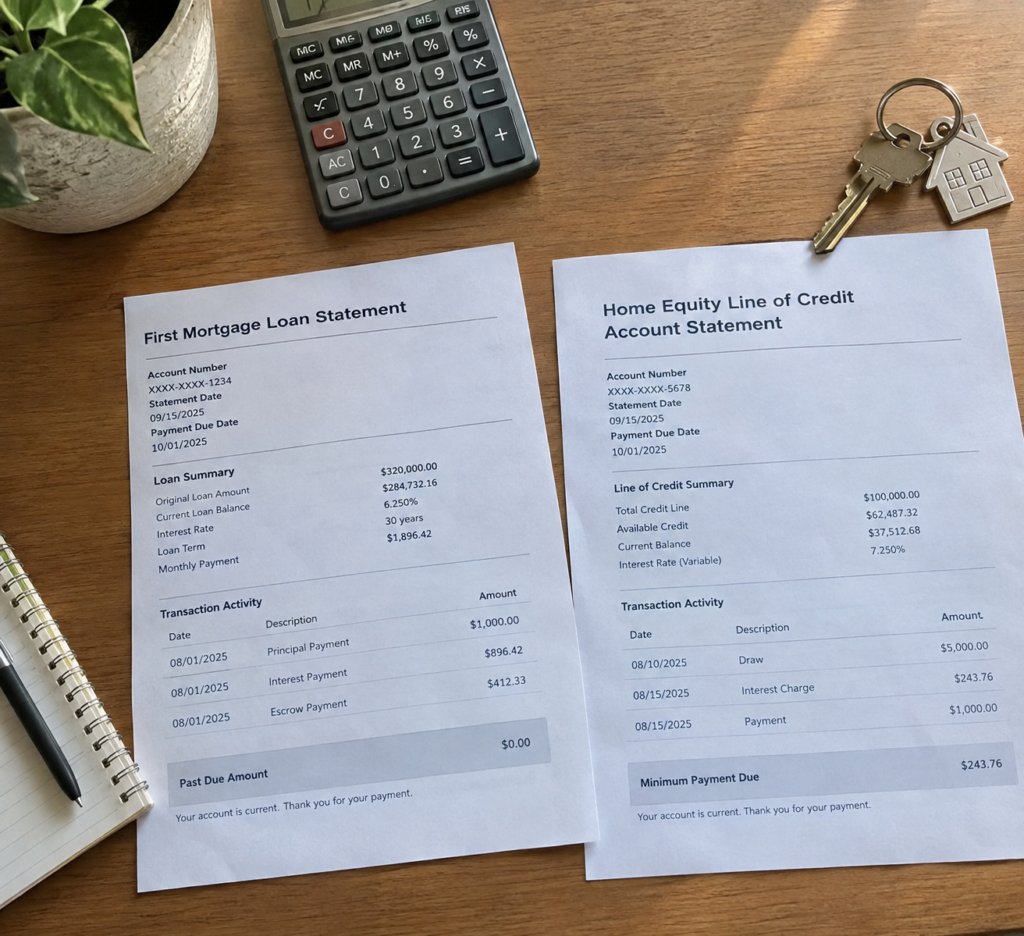
A HELOC (home equity line of credit) or a home equity loan is secured by your house, just like your first mortgage. That means it’s a lien on the property.
When you sell, both loans are paid off at closing, in order:
- your first mortgage is paid first
- your HELOC or second mortgage is paid next
- any other liens are paid after that
- whatever is left goes to you
You don’t need to pay either loan off before you sell. The title or escrow company requests payoff statements from each lender and pays them out of the sale.
What to Check Before You Sell
A few things are worth knowing ahead of time:
- Your payoff amount. Call each lender and ask for a current payoff, not just the balance on your statement. Interest and fees can make them different.
- Whether there’s an early-closure fee. Some HELOCs charge a fee if the line is closed within the first few years.
- Whether the line is still open. Some sellers ask the lender to freeze it once a sale is underway, so the balance can’t change before closing.
- What you’ll net. Add up both payoffs and your selling costs, and compare that to what the house can realistically sell for.
That last step is the one that tells you what kind of sale you’re dealing with.
When There’s Enough Equity
If the house is worth comfortably more than both loans combined, selling is usually simple. Both lenders are paid in full at closing, and you keep the rest.
The second loan doesn’t change much. It just means a smaller check at the end.
One thing that does help: getting your payoff numbers early. Sellers who wait until closing week to request them are sometimes surprised by accrued interest, a recent draw they forgot about, or a fee. Knowing the real number up front means no surprises at the table, and a clearer sense of what you’ll actually walk away with.
When It’s Tight, or You Owe More Than It’s Worth
This is where a second loan matters more.
If the sale price can’t cover both loans plus selling costs, you have a shortfall. Common options include:
- bringing cash to closing to cover the difference
- asking the lenders to accept less than what’s owed, known as a short sale
- holding off on selling, if you can afford to and expect things to improve
Short sales get harder with two lenders. The first lender has to approve the sale. The second lender does too, and it may not agree if it would get little or nothing back. That can mean slower approvals and more back-and-forth.
If that sounds like your situation, our post on owing more than your house is worth goes deeper into the options.
This is general information, not legal, tax, or financial advice. A real estate attorney or tax professional can explain how a short sale or forgiven debt could affect you.
Where Selling Costs Come In
When the margin is thin, selling costs matter a lot.
On a traditional listing, commissions, repairs, closing costs, and months of payments on two loans can eat through the equity you have. Every month the house sits, you’re paying on both.
That’s why some sellers with a second mortgage look at a direct sale. There are no commissions, no repairs, and no months of carrying both loans while you wait for a buyer.
A Simpler Way to Sell
At Fast Ready Offer, we’ve purchased 80+ homes in Clark County, and plenty of them had more than one loan on them. We work with the title company to get both lenders paid at closing, and we buy as-is, so you don’t need to fix anything first.
If you want to see where you’d stand, you can request a no-obligation cash offer. We’ll get you a written offer within 24 hours, and you can line it up next to your payoff numbers before you decide anything.
Close on your terms.
Frequently Asked Questions
Can I sell my house if I have a HELOC?
Yes. A HELOC is paid off from the sale proceeds at closing, after your first mortgage.
Do I have to pay off my HELOC before selling?
No. The title or escrow company requests payoff amounts from each lender and pays them out of the sale.
What happens if I owe more than my house is worth because of a second mortgage?
You may need to cover the gap at closing, wait to sell, or ask the lenders to approve a short sale. With two lenders, both usually have to agree.
Will my HELOC lender charge a fee if I close the line early?
Some do, especially within the first few years. Check your HELOC agreement or ask the lender.
Should I stop using my HELOC once I decide to sell?
It’s generally a good idea, since anything you draw adds to what has to be paid off at closing. Some lenders will freeze the line on request.
Is a home equity loan different from a HELOC when you sell?
They work differently while you have them, but at sale time both are paid off from the proceeds the same way.
Can a cash buyer purchase a house with two mortgages?
Yes. A cash sale pays both loans off at closing, the same as a traditional sale, as long as the sale price covers them or the lenders approve otherwise.